Solarplaza Summit | Energy Storage Germany

Monday 7 December 2026

Day 0 Masterclass

Energy Storage 101

This half-day masterclass provides the foundational knowledge needed to fully benefit from our Energy Storage Germany conference. Covering market mechanics, storage technology, revenue models, and insights into project development, this session is ideal for newcomers, cross-sector professionals, or anyone seeking a clear, practical understanding of the BESS landscape.


Monday 7 December 2026
Energy Strategy Roundtable Dinner

The European Power Shift with Gerard Reid

Europe’s power market is being reshaped by deep electrification, AI demand, and grid constraints. The European Power Shift brings together 16 to 24 decision-makers for a private strategy roundtable and dinner with Gerard Reid. Step away from standard conferences to debate high-stakes energy trends with industry peers. Only 24 seats are available; reserve yours now!


Monday 7 December 2026

19:00

Pre-Conference Networking Event

Enjoy an exclusive pre-conference networking evening at MIA Restobar, a stylish sky lounge high above Düsseldorf’s vibrant MedienHafen. Located on the 16th floor of INNSiDE Düsseldorf Hafen, the venue combines panoramic city views with an elegant Art Deco-inspired setting, creating a sophisticated yet relaxed atmosphere for meaningful conversations and high-level networking. Guests will be treated to drinks and dinner, with local cuisine featuring Spanish influences, carefully selected wines, making it the perfect setting to connect and unwind before the conference begins.
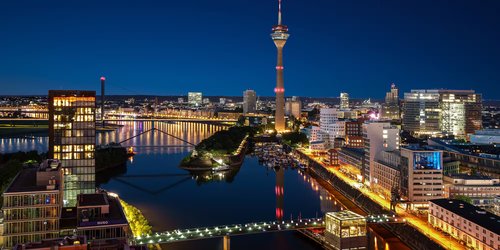
The Networking Event will take place at MIA Restobar

Tuesday 8 December 2026


08:30

Registration & welcome coffee

09:15

Opening words

presentation

15 min.

Dee Yon Chng

Solarplaza


Session 1

Market overview and insights into the storage economy and regulations

09:30

Opening keynote - Germany 2026: the state of Europe's defining BESS market

presentation

20 min.

A market mapping presentation before the day's regulatory and financing conversations land: how big the fleet actually is and where it sits, which operators built it, what they built (1-hour, 2-hour, 4-hour; standalone, co-located, repowered), and how the use cases are evolving from FCR-stacking toward merchant-plus-toll.

  • Installed capacity from 2025 to 2026 and the operators behind the deployment
  • Asset deep dive: geograpical distributtion across the four TSO zones, type and trend of asset built (1-hour, 2-hour, 4-hour; standalone, co-located, repowered)
  • Use case evolution and pipeline reality check: How German residential, C&I, and utility-scale storage compare with other European markets

Read full description

Close description

Sam Wilkinson

S&P Global Energy


09:50

The German storage imperative: latest regulatory changes impacting the storage business case

presentation

20 min.

Deep dive into the latest and upcoming German energy storage regulations impacting the revenues in the BESS Business Case.

  • Latest updates on Flexible Connection Agreements (FCAs)
  • Latest regulatory updates impacting market development for hybrid & co-located projects

Read full description

Close description


10:10

The 2026 German BESS developer playbook: AgNeS, grid connection & supply chain

panel

35 min.

The conversation is built for operators making 2026 capital-allocation decisions: what changes, when, by how much, and where the upside opportunities sit inside the disruption.

  • Development implications for the latest regulations
  • AgNeS in practice, BKZ post the BGH ruling, EEG state-aid expiry and what replaces it, 2026 capacity-market tenders 
  • What developers, investors and asset owners are doing differently in 2026

Read full description

Close description

moderator

Oliver Schmidt

Imperial College London

Marie-Sophie Braun

Kyon Energy


10:45

Morning networking break

Session 2A

Grid & Regulation

11:30

Inside the new grid connection regime: process, timelines and the co-location question

presentation

20 min.

A direct view from network operators on the "first-ready, first-served" maturity-based procedure replacing first-come, first-served, MiSpeL's mid-2026 implications, and how co-location applications are actually being processed.

  • The Reifegradverfahren in practice: maturity scoring, cyclical processing windows, and how applications are now ranked
  • MiSpeL and the co-location grid application: what changes when hybrid systems can charge from the grid
  • Where the DSO–TSO coordination is breaking down today, and where the TSOs are pushing for fixes

Read full description

Close description


11:50

The grid connection reality: a developer's view from inside the process

presentation

20 min.

A first-person account from a developer who has navigated the connection regime in 2025-26: what worked, what failed, and what they'd do differently on the next project.

  • Where retroactive applications and DSO process chaos hit the project timeline
  • The co-location application in practice: what got approved, what got rejected, and why
  • Practical lessons for projects entering the connection queue in 2026

Read full description

Close description


12:10

The co-location challenge: navigating Grid, tech and MiSpeL

panel

35 min.

How network operators and developers are working through the co-location grid connection question: where the friction lies, what the process changes entail, and what needs to change next.

  • The retroactive application problem: where does responsibility sit, and what gets resolved in 2026?
  • The DSO–TSO coordination gap on co-located projects: who decides what, when
  • What technology best supports a grid connection regime for hybrid projects

Read full description

Close description

moderator

Wojtek Swietochowski

ABO Energy

Jeremias Schleeger

TenneT


Session 2B

Finance & fiscal environment

11:30

The German BESS incentive stack: subsidies, tax and fiscal levers in 2026

presentation

20 min.

A practitioner walkthrough of the incentives shaping German BESS project economics: from the 50% accelerated depreciation and 10% VDE 2510 tax credit to KfW financing, EEG co-location support, and what changes when state aid expires on 31 December 2026.

  • The 2026 tax and depreciation stack, and how it flows into project IRR
  • KfW, EU Innovation Fund, and other public capital routes developers are actually using
  • The post-31 December landscape: what replaces EEG state aid for co-located projects, and what it means for hybrid economics

Read full description

Close description


11:50

Co-located vs standalone in Germany: where the bankable economics actually sit

presentation

20 min.

A project-level financial view of when co-located PV+BESS is the right answer in Germany and when standalone wins: modeled under three AgNeS scenarios and the post-MiSpeL regulatory landscape.

  • The co-location premium quantified: grid-fee impact, imbalance cost reduction, and where the value actually sits
  • AgNeS sensitivity: how the €4–7/kW/yr capacity fee scenario and the FID window reshape co-located vs standalone IRRs
  • Sizing the asset: 2h vs 3h vs 4h duration, and where the diminishing returns kick in for German projects

Read full description

Close description


12:10

Building bankable German BESS: how developers, lenders and investors are structuring 2026 deals

panel

35 min.

A working discussion between the people actually closing German BESS deals in 2026: how they're structuring the FID window, what lenders need to see, and how the merchant-plus-toll model is being priced.

  • The six-month FID sprint: what "binding" means in practice, and how developers are locking in supply chain, connection, and financing simultaneously
  • What a lender's credit committee is actually asking about German BESS in 2026: from AgNeS grandfathering to FCA operational envelope
  • Merchant, tolling, hybrid: how deals are being structured, and where each model wins

Read full description

Close description

moderator

Max Stirling

JLL

Afrida Kabir

Encavis

Max von Hausen

Pexapark
Quirin Müller

ABN AMRO Bank


12:45

Networking lunch break

Session 3A

The next wave: C&I, scale and the supply chain reality

14:15

The trends shaping large-scale BESS: duration, siting and the post-thermal grid

presentation

20 min.

A forward-look on where the German large-scale BESS market is heading: from the shift toward 4-hour and longer durations to optimal siting decisions and the grid role BESS takes as conventional plants retire.

  • Duration and system size: why 2-hour is the floor, 4-hour is the new normal, and where 6-hour and beyond fit in
  • Optimal siting: how the value of location changes as the grid decarbonizes
  • BESS as replacement infrastructure: what happens to the market as coal and gas phase out

Read full description

Close description


14:35

C&I storage in Germany: the market beneath the headlines

presentation

20 min.

The C&I story the utility-scale conversation misses: from the tax-driven payback economics to the offtaker dynamics driving corporate deployment.

  • The 2026 C&I payback picture: 50% accelerated depreciation, VDE 2510 tax credit, and where projects are actually pencilling
  • What corporates like BASF, Mercedes and BMW are actually procuring: behind-the-meter, corporate PPA, on-site hybrid
  • The C&I supply chain: why the constraints are different from utility-scale and what that means for developer strategy.

Read full description

Close description


14:55

Scaling German BESS: supply chain, EPC capacity and the constraints on the next 5 GW

panel

35 min.

A working discussion between manufacturers, EPCs, developers and technical advisors on what's genuinely constraining the next wave of German BESS: from cell supply and PCS lead times to EPC bandwidth and standardization.

  • Where the supply chain is actually tight in 2026: cells, PCS, transformers, EPCs, and what breaks first
  • Standardization and interoperability: what's now a bankability minimum, and where lenders are drawing the line
  • The China question: tariffs, cybersecurity, and how developer procurement strategies are shifting

Read full description

Close description


Session 3B

The tricks of the trades: revenue strategies & market participation

14:15

The 2026 German revenue stack: what's actually paying, and what's cannibalizing

presentation

20 min.

A data-led breakdown of where German BESS revenue is genuinely coming from in 2026: from FCR saturation and aFRR compression to intraday spreads, negative-price arbitrage, and the emerging Momentanreserve stack.

  • The revenue mix behind operational German BESS: what worked in 2025 vs what's working now
  • FCR, aFRR, mFRR: where saturation is biting and where it isn't
  • Momentanreserve and dynamic grid fees: the two new revenue streams and how operators are pricing them in

Read full description

Close description


14:35

Trading BESS in Germany: strategy, algorithms and the operator's playbook

presentation

20 min.

A practitioner walkthrough of what advanced trading actually looks like on German BESS assets: from co-optimization across markets to the algorithmic edge, and where human judgment still matters.

  • Cross-market co-optimization: how leading operators stack day-ahead, intraday, balancing, and capacity within a single asset
  • Algorithmic trading and forecasting: where machine learning genuinely lifts revenue vs where it's marketing
  • Real-world operator lessons: what German assets are actually earning, and how the top quartile pulls away from the median

Read full description

Close description


14:55

Beyond the algorithm: aggregator strategies and the German market's next revenue frontier

panel

35 min.

A working discussion between optimizers, aggregators, and asset owners on what's next after FCR saturation: from Momentanreserve to virtual power plant strategies to the corporate offtake bridge.

  • The Momentanreserve reality: who's actually eligible, who's already bidding, and where the €4–7k/MW/yr math nets out
  • Aggregation at scale: how the best VPP operators are pricing multi-asset flexibility across residential, C&I, and utility
  • The offtake bridge: how tolling, corporate PPAs and merchant blends are reshaping the revenue conversation

Read full description

Close description

Harald Ott

Verbund


15:30

Afternoon networking break

Session 4

Future outlook: visions on the future of Germany's integrated solar & storage landscape

16:15

Germany's energy transition horizon: market forecasts for integrated solar PV & storage

presentation

20 min.

A forward-look at market-based flexibility signals: how the UK uses locational pricing and system-service markets to steer battery deployment to where the grid needs it, and what a German version could look like.

  • How UK locational signals actually work in 2026: NESO's approach, capacity market zoning, and where BESS is being pulled to
  • The German equivalent question: dynamic grid fees, potential bidding zone splits, and what a market-based approach beyond AgNeS looks like
  • What Germany could learn: and what wouldn't transfer

Read full description

Close description


16:35

Where the demand comes from: data centres, industrial electrification and Germany's post-2030 load story

presentation

20 min.

The demand-side question that reshapes the BESS business case: how data centers, green steel, e-mobility charging and industrial electrification are set to change German electricity demand, and what that means for storage siting, sizing and revenue.
  • The demand tsunami: data center buildout, green industry electrification, and what BNetzA's own load forecasts now show
  • What this does to wholesale spreads and where BESS revenues land
  • Regional asymmetry: which Länder are absorbing the demand growth and where new co-location opportunities emerge

Read full description

Close description

Robert Kroon

Arcadis


16:55

The German storage roadmap: charting the next decade

panel

35 min.

From utility-scale operators to C&I, residential and mobile storage: industry leaders come together to chart a shared vision for how German storage evolves through 2030 and beyond, and to identify the system-level conflicts that need resolving.

  • Utility-scale, C&I, residential, and mobile perspectives on the next wave of growth and value
  • Where each segment sees the strongest opportunities
  • How regulation, capacity market design, and Germany's energy-system strategy will guide developer decisions through 2030

Read full description

Close description

Sophia Truong

Sunrock


17:30

Closing remarks

presentation

5 min.


17:35

Networking drinks

Got questions?

We’ve got you covered — explore our most frequently asked questions about Solarplaza Summit Energy Storage Germany!

Prefer to reach out?

Send us an email; we’d be more than happy to help.

Radmyla Nikitchenko
Junior Event Manager

For practical questions regarding our activities:

[email protected]

Dee Yon Chng
Project Manager

For questions about the program and content of the event:

[email protected]

Santiago Guillon Margozzini
Business Developer

For questions regarding partnership opportunities:

[email protected]