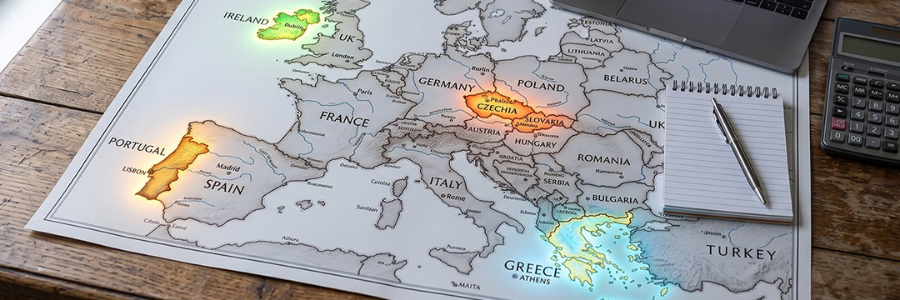
Recent developments in Czechia, Portugal, Ireland and Greece show that storage deployment is moving closer to execution—but through four different routes. New operating assets, grid-capacity procedures, tariff reform and merchant-return forecasts reveal where progress is tangible and where commercial risk remains unresolved.
In July, Solarplaza’s article Europe’s next BESS wave: market drivers and localized returns examined the long-term investment case for storage in Czechia, Portugal, Ireland and Greece. In the weeks since, new project milestones, regulatory decisions and market data have sharpened the picture.
The four countries share a growing need for flexibility as renewable generation expands and grid constraints become more visible. Storage is not, however, advancing through a single European playbook. Czechia is gaining its first operating evidence of large-scale revenue stacking. Portugal is preparing to allocate scarce grid capacity before a stable revenue framework is fully in place. Ireland is combining tariff reform with a dedicated route to market for long-duration storage. Greece is testing whether attractive modeled returns can be converted into financeable projects with secure grid access.
Key takeaways
- Czechia is moving from regulatory preparation into physical delivery. The country connected 318 MWh of new battery capacity in the first half of 2026, while the 57 MW/120 MWh Lipnice project has become its largest operational BESS.
- Portugal is opening more than 1 GVA of grid capacity to storage, but not yet providing equivalent revenue certainty. Proposed procedures cover up to 750 MVA of standalone storage and 300 MVA of renewable projects with co-located batteries.
- Ireland is creating a dedicated route to market for multi-hour storage. National policy supports procurement of up to 500 MW of storage with a minimum four-hour duration, while EirGrid has proposed a first phase of at least 201 MW.
- Greece combines strong modeled returns with one of Europe’s most crowded storage pipelines. Aurora Energy Research estimates that a two-hour BESS entering operation in 2027 could achieve an IRR of approximately 11–12%, but 12.15 GW of merchant applications are competing within a 4.7 GW priority framework.
Czechia: operational assets begin testing the revenue stack
Czech battery deployment accelerated considerably during the first half of 2026. According to Solární Asociace, 318 MWh of battery capacity was connected between January and June, representing an 83% increase from the same period in 2025. The total covers both batteries paired with solar installations and standalone assets. Within the standalone segment, 12 systems with a combined capacity of 108 MWh were connected.
The association links this growth to the opening of the Czech market under Lex OZE III, which formally recognized storage, aggregation and flexibility within the energy system. It also warns that the next phase of development will be limited by transmission and distribution capacity, as well as by the final design of tariffs and market regulation.
The most important recent Czech headline is not another connection request, but a project that is already operating. SUAS Group and Slovak investment firm EIF brought the 57 MW/120 MWh Lipnice BESS into operation at the end of July. It is currently the largest operational battery in Czechia, ahead of the recently commissioned 37.95 MW/41.7 MWh Modlany system.
Lipnice will not depend on a single service. Its owners intend to operate it primarily in the day-ahead and intraday electricity markets, while also offering ancillary services to transmission system operator ČEPS when pricing is attractive. SUAS Group and EIF estimate a payback period of five to eight years, although this remains a company projection rather than an independently verified outcome. The project will therefore provide an early test of whether algorithmic trading and revenue stacking can support utility-scale Czech batteries as balancing-market revenues become more competitive.
A second potential revenue route is taking shape over a longer horizon. On 16 July, the European Commission approved a market-wide Czech capacity mechanism that will be open to generation, storage and demand response. Its first delivery period is scheduled for November 2030 to October 2031. This will not solve the near-term business case for projects entering operation today, but it could eventually add availability-based income to the Czech revenue stack.
The Czech market is consequently entering a more demanding stage. Legislative recognition and a large pipeline have created momentum; operating performance, connection capacity and the durability of merchant revenues will now determine how much of that pipeline is repeated at scale.
Portugal: grid capacity opens before revenue certainty
Portugal’s storage ambitions are rising from a very low starting point. The country had commissioned only around 20 MW of battery storage by the end of 2025. Its National Energy and Climate Plan set a target of 2 GW by 2030, while the more recent National Energy Storage Strategy raises the proposed ambition to 3 GW by 2030 and 4.5 GW by 2040.
The immediate policy focus is grid access. Portugal’s Directorate-General for Energy and Geology has consulted on two separate competitive procedures:
- Up to 750 MVA of injection capacity for standalone storage facilities, distributed across several transmission-network locations.
- Up to 300 MVA for new renewable projects with co-located storage, including proposed capacity in Abrantes, Rio Maior, Sines and Santo André.
Both procedures are designed as electronic auctions for the right to use available grid injection capacity. Together, they could unlock up to 1.05 GVA of new grid-connected renewable and storage projects.
The distinction between grid access and revenue support is critical. The proposed procedures do not automatically guarantee storage projects a capacity payment or fixed availability income. APREN, the Portuguese renewable energy association, has warned that the projects are expected to remain fully exposed to market revenues under the present design. Licensing speed, connection delivery and the creation of sufficiently stable revenue streams will therefore decide whether auction winners can secure financing.
Portugal is addressing the physical side of the equation as well. On 6 August, the government approved a €1.58 billion distribution-network investment plan for 2026–2030. The programme is intended to increase distribution capacity and reduce constraints affecting the connection of new generation, demand and storage projects. It should not be interpreted as a €1.58 billion storage-support fund; it is wider network infrastructure investment that may make more storage projects connectable.
Portugal is therefore assembling several of the components required for a utility-scale BESS market: a national ambition, competitive grid allocation, co-location opportunities and network reinforcement. The unresolved component is the commercial bridge between winning capacity in an auction and presenting lenders with a bankable revenue case.
Ireland: long-duration procurement meets tariff reform
Ireland’s official near-term storage framework is more modest—and more actionable—than the extreme multi-gigawatt estimates that have recently appeared in industry headlines.
The government’s Electricity Storage Policy Framework supports the procurement of up to 500 MW of storage capable of importing and exporting continuously for at least four hours. EirGrid has proposed implementing this through a phased qualification and tender process, beginning with a minimum of 201 MW across at least three projects. The system operator has also acknowledged that available transmission connections will limit the volume that can be delivered within the required timeframe.
The proposed design attempts to balance revenue certainty with continued market participation. EirGrid’s consultation describes a mechanism under which successful long-duration storage assets would remain active in wholesale and system-service markets while receiving protection against insufficient market revenues. Detailed rules for the proposed revenue floor and settlement arrangements remain subject to further development.
Network charging has also moved in a more favorable direction. In June, the Commission for Regulation of Utilities decided that energy storage units should be subject to Generation Transmission Use of System charges rather than Distribution Use of System charges. The decision does not remove all network charges, but it addresses a significant disincentive to wholesale-market participation by treating storage more consistently with generators.
The underlying need for flexibility is becoming more visible. Ireland’s Central Statistics Office reported that grid-scale solar farms generated 1,101 GWh in 2025, 51% more than in 2024. On 11 August 2026, grid-scale solar reached a record output of 1,258 MW, providing approximately one-third of national electricity use at that moment. At the same time, EirGrid reported that 11.2% of combined wind and solar generation was dispatched down during the first half of 2026.
Investment activity is beginning to reflect this need. On 20 August, Capital Dynamics announced the acquisition of the 170 MW, four-hour Knockanure BESS project in County Kerry. The ready-to-build project has planning consent and secured connection capacity at the neighboring 110 kV substation, with procurement and delivery planning now underway. The transaction offers a more concrete market signal than a theoretical national storage requirement: investors are assigning value to projects that have already secured planning and grid access.
Ireland is thus moving beyond a storage market dominated by short-duration balancing services. The next phase will depend on whether the LDES procurement provides sufficient downside protection without preventing projects from stacking wholesale, capacity and system-service revenues.
Greece: attractive returns meet a crowded connection queue
Greece has one of Europe’s clearest physical cases for energy storage. Research presented by Pantelis Biskas at a seminar hosted by Greek solar-producer association POSPIEF estimates that renewable curtailment could reach between 3.3 TWh and 3.7 TWh in 2026, compared with approximately 2 TWh in 2025. At the upper end of the range, curtailment would amount to roughly 12% of annual renewable generation. These figures are forecasts rather than measured full-year results, but they illustrate the growing exposure of Greek renewable assets to grid constraints and periods of surplus generation.
The near-term merchant economics appear attractive. Analysis by Aurora Energy Research indicates that a two-hour standalone BESS entering operation in 2027 could achieve an IRR of approximately 11–12%. Aurora attributes this opportunity partly to elevated power-price volatility and Greece’s continued exposure to developments in international gas markets.
However, the consultancy also cautions that part of this upside may be temporary rather than structural. Policy intervention, lower volatility and increasing competition between batteries could reduce spreads before projects entering operation later in the decade have recovered their investment. Aurora estimates that an equivalent project commissioned in 2030 could generate an IRR approximately two percentage points lower.
The project pipeline is considerably larger than the capacity the country currently intends to prioritize. Investors submitted applications for 12.15 GW of utility-scale merchant batteries, compared with approximately 4.7 GW of standalone projects expected to receive priority grid treatment. Applications submitted to the transmission system operator represented approximately 10 GW, while a further 2.15 GW was submitted to the distribution system operator.
This level of oversubscription demonstrates strong developer interest, but not necessarily an executable 12.15 GW market. Projects must still be ranked, secure connection conditions and convince lenders that merchant revenues will remain sufficiently predictable. Greece’s earlier subsidized storage tenders also show the distinction between awarded capacity and operational capacity: approximately 900 MW was awarded through three auction rounds, but connection delays have prevented much of that capacity from entering commercial operation on schedule.
Progress is also becoming visible in the co-located segment. In August, Energypress reported that connection terms for batteries sharing grid access with renewable projects were expected to approach 500 MW, covering approximately half of the 1 GW allocation under the relevant framework. Once final connection terms are secured, developers can begin arranging project financing, although lenders are expected to differentiate strongly between established energy companies and smaller project owners. As this figure comes from industry reporting rather than a published system-operator dataset, it should remain attributed to Energypress.
A further execution signal comes from ContourGlobal. The company acquired a 500 MW/2 GWh Greek BESS portfolio in January, including the 100 MW/400 MWh Taxiarches project and up to 400 MW/1.6 GWh of additional projects. The wider portfolio is not uniformly ready to build, but Taxiarches is more advanced. In an August supply agreement with CATL, ContourGlobal stated that the four-hour Taxiarches facility was already under construction.
For Greece, attractive modeled returns are therefore only one part of the investment case. The genuinely scarce assets are credible connection rights, clearly defined operating conditions and projects capable of reaching financial close before the current revenue opportunity narrows.
Four markets, four execution tests
Taken together, the latest developments show that Europe’s emerging BESS markets are not simply following mature storage markets with a time delay.
Czechia is beginning to produce operational evidence. Its first large batteries will demonstrate whether day-ahead trading, intraday arbitrage and ancillary services can support sustainable returns as competition increases.
Portugal is creating access to the grid at scale, but developers may need to accept considerable merchant exposure unless a capacity or availability-based mechanism is added.
Ireland is taking a more structured route through tariff reform and dedicated LDES procurement. Its challenge will be balancing revenue certainty, market participation and the limited availability of suitable transmission connections.
Greece has no shortage of projects or modeled returns. Its decisive test is converting an oversubscribed application pipeline into connected and financeable assets before market conditions change.
The need for storage is no longer the central question in any of the four countries. The more relevant question is which projects can combine secure grid access, suitable duration, a credible revenue stack and financing terms that survive changing market conditions.
Connecting national developments to the Solarplaza Seminar BESS series
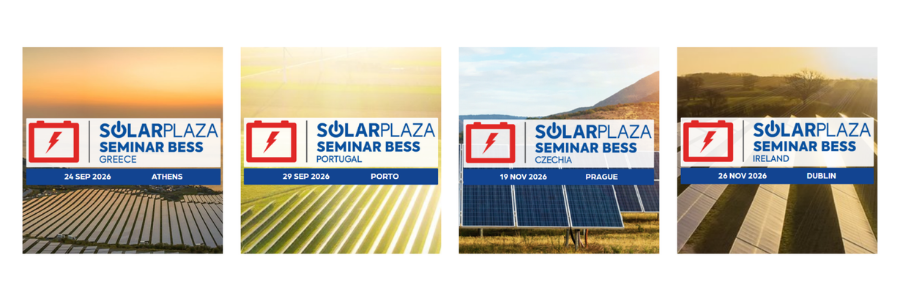
These differences are why the upcoming Solarplaza Seminar BESS events approach each country separately. Developers, investors, IPPs, financiers and service providers will examine the regulations, grid procedures and revenue structures specific to each market:
- Solarplaza Seminar BESS Greece — 24 September 2026, Athens
- Solarplaza Seminar BESS Portugal — 29 September 2026, Porto
- Solarplaza Seminar BESS Czechia — 19 November 2026, Prague
- Solarplaza Seminar BESS Ireland — 26 November 2026, Dublin
Each program focuses on the local market and regulatory outlook, project bankability and financing, and the revenue models required to move storage projects from application pipelines into commercial operation.
