South Africa has 25 licensed electricity traders. None of them trades electricity as a financial product. That single figure, shared during our 5 November 2026 webinar 'Ready to trade? Preparing your business for Southern Africa's new electricity markets', sums up where the region stands: the doors are opening, but the capabilities to walk through them are still being built.
Moderated by Hans-Arild Bredesen, CEO of Bredesen Consulting, the session brought together Longo Chellah, Trading Manager at Africa GreenCo, and Matthew le Cordeur, just energy transition and infrastructure research specialist at Krutham. Here is what they covered.
Key takeaways
- The markets are opening: Namibia, Zambia, and South Africa are leading a region-wide shift away from vertically integrated utilities, with Mozambique, Zimbabwe, Lesotho, and Eswatini following.
- South Africa targets April 2027: The South African Wholesale Electricity Market (SAWEM) plans external go-live in April 2027, full balancing from Q1 2028, and capacity and ancillary services markets in 2030. The timeline is a target, not a commitment.
- Trading is a data business: A single 25-year power purchase agreement (PPA) generates 219,000 hourly data points for one price parameter, and 1.53 million across seven. Spreadsheets don't survive that.
- The reference price comes first: Every hedge and future depends on a credible price, and in South Africa that hinges on how Eskom's vesting contracts are designed.
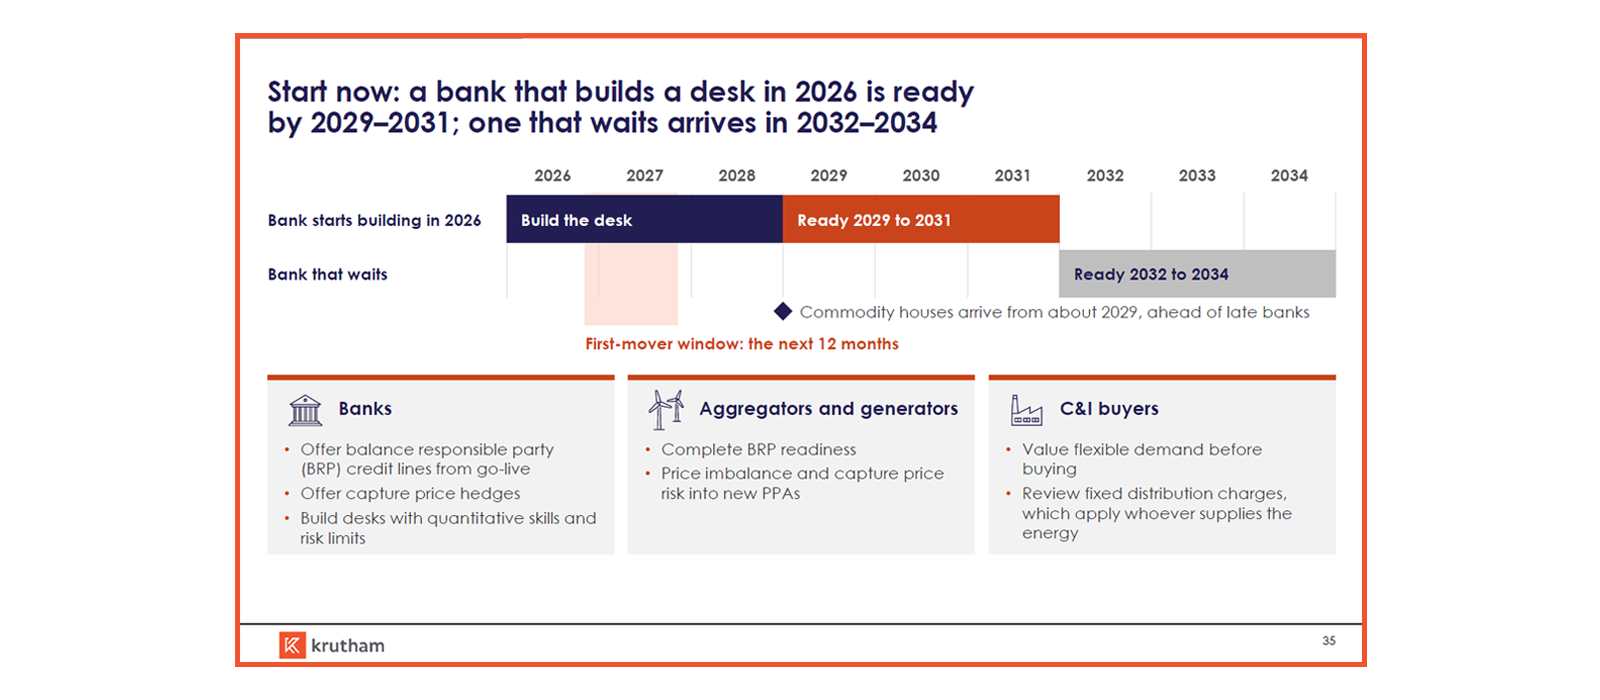
- Banks have a 12-month window: A bank that starts building a trading desk in 2026 could be ready by 2029 to 2031. One that waits arrives in 2032 to 2034, after the commodity houses.
A region moving from utilities to markets
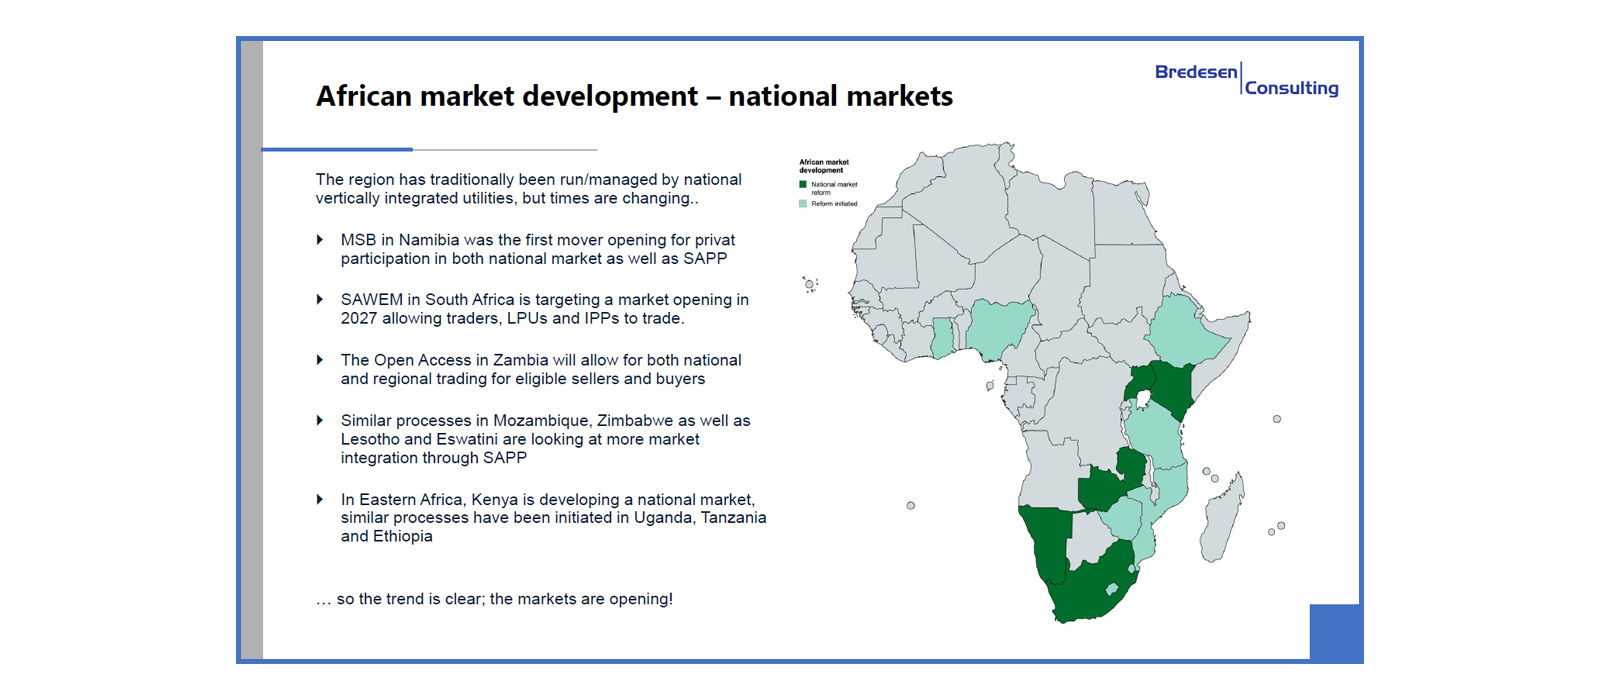
Bredesen opened by setting the scene. Africa's power sector has long been run by national, vertically integrated utilities, but that is changing fast in Southern Africa. Namibia's modified single buyer model was the first mover, opening both its national market and access to the Southern African Power Pool (SAPP) to private players. Zambia's open access regime allows eligible sellers and buyers to trade nationally and regionally. South Africa's wholesale market is next in line.
The momentum isn't limited to the south. Kenya is developing a national market, with similar processes underway in Uganda, Tanzania, and Ethiopia. The Eastern Africa Power Pool (EAPP), established in 2005 on the same design principles as SAPP, is targeting a regional market opening in 2027. A new interconnection between Tanzania and Zambia is set to link the two pools, with a 2028 target. Further out, the African Single Electricity Market (AfSEM) is gaining traction. As Bredesen put it: 'The trend is very clear. The markets are opening.'
Inside a regional trading desk
Africa GreenCo has been trading on SAPP since 2021, when it became the pool's first market participant member. Since then it has traded more than 4 TWh, signed around 1,000 MW of renewable PPAs, and built a team of 80+ people across the region, with a full trading desk in Lusaka. It is licensed to trade in Zambia, South Africa, Zimbabwe, and Namibia.
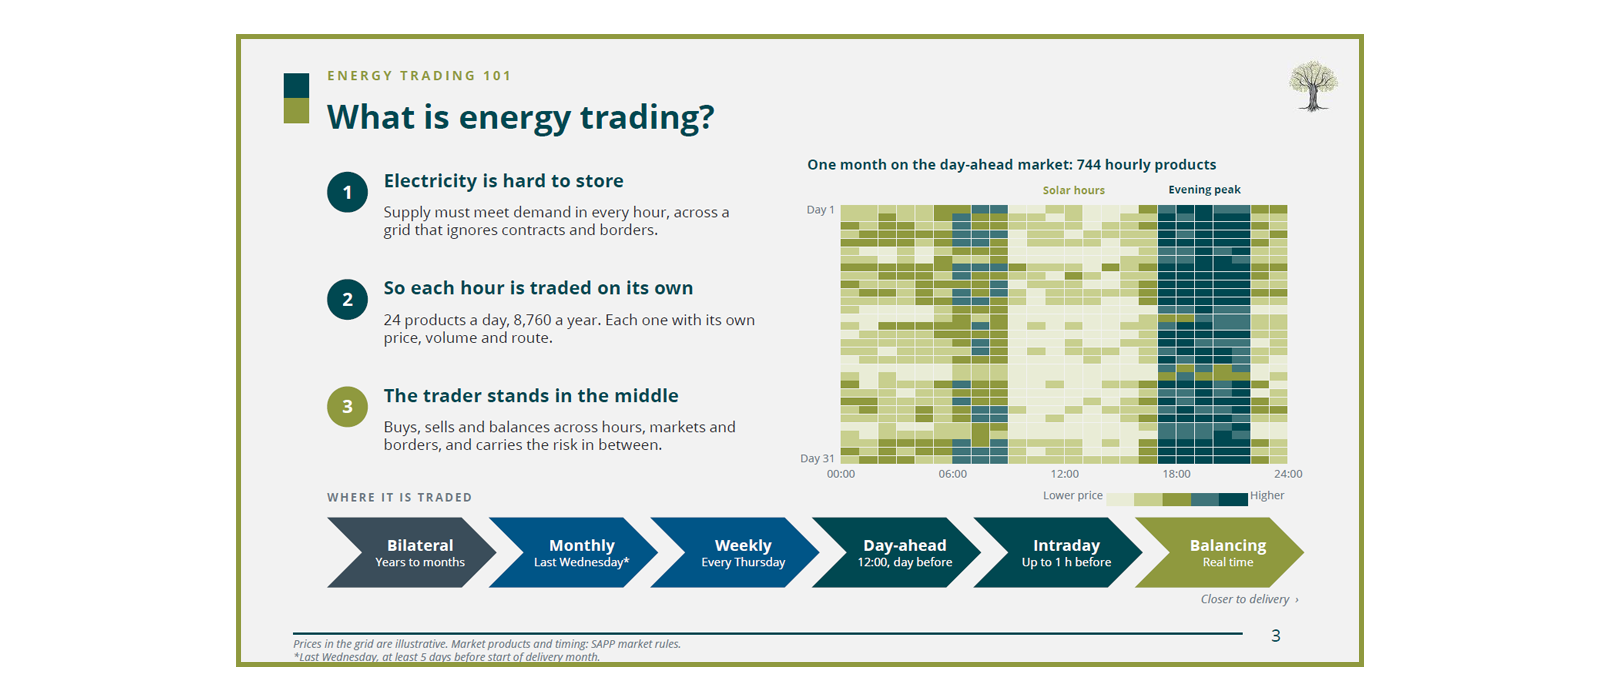
Chellah walked through what that desk actually does. Because electricity is hard to store, each hour trades as its own product: 24 a day, 744 a month, 8,760 a year, each with its own price, volume, and route. On SAPP, those products trade across bilateral, monthly, weekly, day-ahead, intraday, and balancing markets.
A typical day starts with market analysis of prices, weather, and line capacity, followed by bilateral nominations. Day-ahead bids close at noon the day before delivery. Results are booked into the energy trading and risk management (ETRM) system, trades are confirmed, schedules sent, and after delivery the meter data, reconciliation, invoicing, and settlement follow. Front office trades, middle office controls risk and positions, and back office settles. Every day of the year.
The scale of the data is what makes an ETRM essential. One hour of margin already involves the sell price, buy price, wheeling, transmission losses, balancing, and fees. Multiply that across a 25-year contract and a portfolio, and the numbers run into the millions. GreenCo built its ETRM in-house, and Chellah stressed automating data pipelines to cut errors and keep a full audit trail.
Errors are expensive. Chellah highlighted three common failures:
- Missed gate closure: No bid means no position, and the gap is bought or sold at whatever price the market gives.
- Wrong schedule: Any deviation between schedule and meter is charged as imbalance.
- Unreconciled settlement: Small hourly differences add up to real money over a month.
For companies weighing whether to build these capabilities or outsource them, Chellah suggested five questions to put to any provider: who carries imbalance risk, are market costs passed through at cost, who owns the data and history, how quickly can you see your own position, and how do you exit.
SAWEM: a staged opening
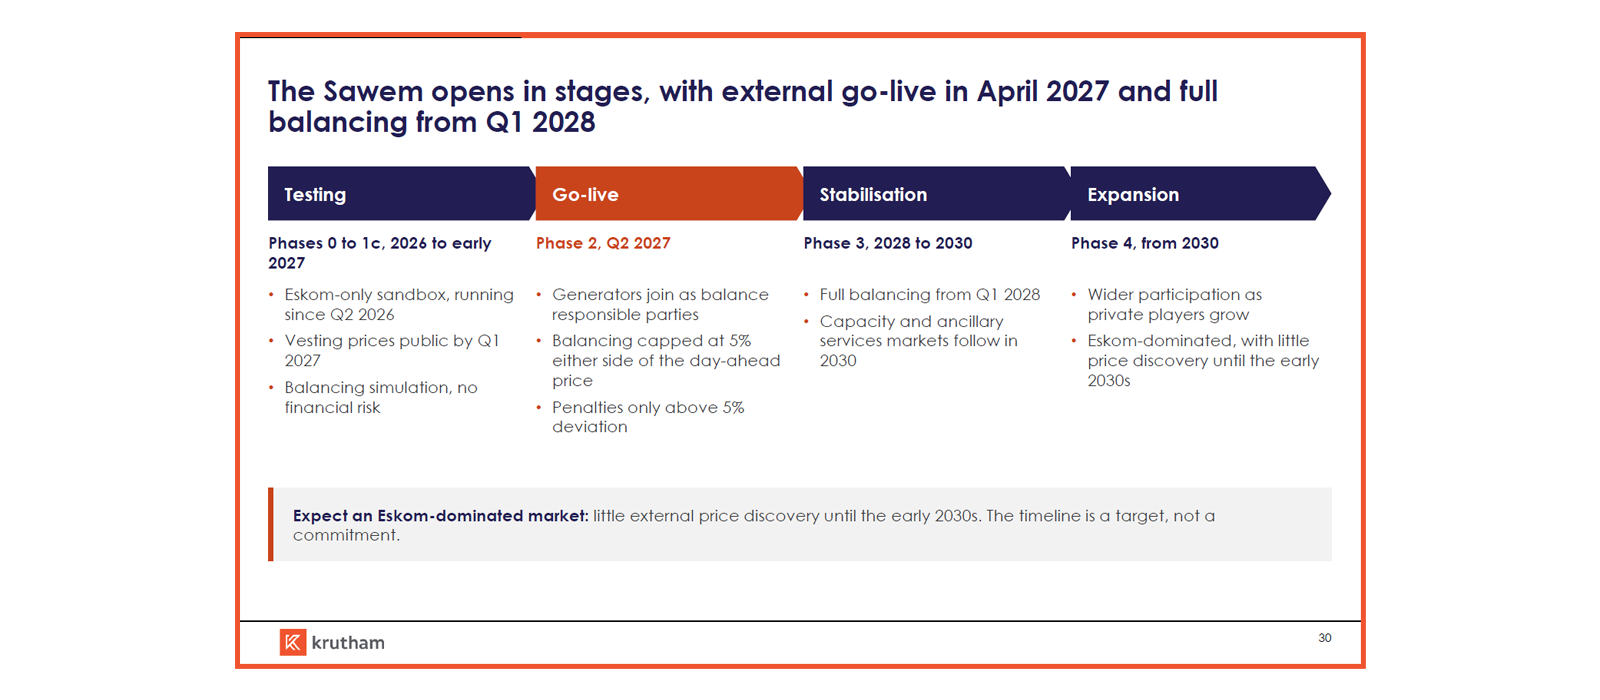
Le Cordeur turned to SAWEM, run by the National Transmission Company South Africa (NTCSA). It has been live since Q2 2026 as an Eskom-only sandbox where no real money changes hands. The first real milestone is the publication of vesting prices, expected by Q1 2027, which will provide the first transparent wholesale price signal. External go-live is targeted for April 2027.
At go-live, generators join as balance responsible parties (BRPs), with balancing capped at 5% either side of the day-ahead price and penalties only above a 5% deviation. Full balancing follows from Q1 2028, and capacity and ancillary services markets in 2030. Generators of 10 MW or more, and the traders and distributors contracting with them, must register as BRPs even if they never trade. Participant onboarding, including API access, opened in October 2026.
Le Cordeur was realistic about what comes next: with up to 90% of volumes under Eskom vesting contracts, he expects an Eskom-dominated market with little external price discovery until the early 2030s.
Why the reference price matters
Today, South Africa's licensed traders are mostly IPP-linked aggregators running bilateral contracts and absorbing imbalances in-house. SAWEM changes that by creating three exposures. Generators face capture price risk, because they earn the average price for the hours they produce. Retailers face volume and price risk. And imbalances get settled against a price that doesn't yet exist.
Financial instruments are how that risk gets shared, but only once there is a reference price people trust. Le Cordeur pointed to the vesting contracts as the key near-term lever. Of the draft options, one leaves Eskom less than 10% exposed to the market, which Krutham considers too little. A 40% option with a fixed-date reduction would do more to create volume for financial trading. Krutham's proposed sequence: publish a transparent fixed and variable cost split, have Eskom bid at short-run marginal cost, phase vesting out at capacity milestones or fixed dates, and publish a machine-readable price series.
One word of caution: an accurate price will be a low one, below the cost of new solar in most hours. As Le Cordeur put it: 'A low price shouldn't be seen as market failure.'
Regulation and capital
A common assumption is that regulators must build a derivatives regime for electricity from scratch. They don't. Cash-settled electricity contracts already fall under the Financial Markets Act's over-the-counter (OTC) derivative rules, supervised by the Financial Sector Conduct Authority (FSCA). The gaps lie in application: where physical settlement ends and derivative rules begin, and whether a National Energy Regulator of South Africa (NERSA) license can substitute for authorization under the Act. NERSA's draft trading platform framework, published on 28 September 2026, mentions neither the FSCA nor derivatives.
Capital is the second constraint. Banks apply full Basel III rules, so a 12-year hedge with a BB-rated IPP will be costly. Guarantees from development finance institutions (DFIs) and the Credit Guarantee Vehicle could bring that cost down.
Le Cordeur expects bilateral financial swaps from SAWEM's launch in April 2027, market-operator contracts from April 2030 at the earliest, and standardized futures between 2031 and 2033. The first products will likely be capture price hedges for IPPs and battery energy storage system (BESS) revenue swaps, in which an operator receives a fixed rand amount per MW per year. The catch: South Africa has no credible index for intraday battery revenue yet.
Questions from the audience
On that battery index, Bredesen noted that SAWEM's market operator will optimize battery dispatch itself, which makes a standalone index harder to derive. An index could instead be built from market price volatility, as is happening in Europe, where Nord Pool and a partner recently launched one.
Asked about market power in an Eskom-dominated market, Bredesen argued that price discovery will still be meaningful, as vesting contracts regulate Eskom's bids at marginal cost across many gigawatts of capacity. Market conduct rules apply, with surveillance by both the market operator and NERSA.
On liquidity, Chellah offered perspective: Nord Pool trades over 1,000 TWh a year, and SAPP volumes are less than 1% of that. Transmission capacity and regulatory hurdles in host countries, such as balancing agreements and licensing, remain constraints, but membership is growing fast. Both he and Bredesen expect SAWEM and SAPP prices for the South African zone to converge, given that SAWEM covers a roughly 50,000 MW system while SAPP's day-ahead market typically clears under 1,000 MW.
What to do now
The speakers agreed that readiness can't wait for the market. Le Cordeur's recommendations for the next 12 months:
- Banks: Offer BRP credit lines and capture price hedges from go-live, and build desks with quantitative skills and risk limits.
- Aggregators and generators: Complete BRP readiness and price imbalance and capture price risk into new PPAs.
- Commercial and industrial (C&I) buyers: Value flexible demand before buying, and review fixed distribution charges, which apply whoever supplies the energy.
For the banks in particular, the message was blunt: 'If the banks want to play in this space, they need to do so now.'
The conversation continues in person at the Solarplaza Summit RE Trading Southern Africa on 2 December 2026 in Johannesburg. The full webinar recording and slides are available on solarplaza.com.

